2026 Social Security Update: 2.8% COLA Impact on Retirement
Anúncios
The 2026 Social Security update, featuring a projected 2.8% COLA, aims to help retirees maintain purchasing power amid inflation, directly impacting their monthly benefits and long-term financial stability.
Anúncios
As we look ahead to financial landscapes, the anticipated 2026 Social Security Update: What a 2.8% COLA Means for Your Retirement Benefits stands as a critical topic for millions of Americans. This adjustment, designed to help retirees keep pace with living costs, directly influences the financial well-being of beneficiaries. Understanding its implications is essential for effective retirement planning.
Understanding the Cost-of-Living Adjustment (COLA)
Anúncios
The Cost-of-Living Adjustment, or COLA, is a vital mechanism designed to protect Social Security beneficiaries from the eroding effects of inflation. Each year, the Social Security Administration (SSA) reviews economic data to determine if an adjustment is necessary. This ensures that the purchasing power of benefits doesn’t diminish over time, allowing retirees and other beneficiaries to maintain their standard of living.
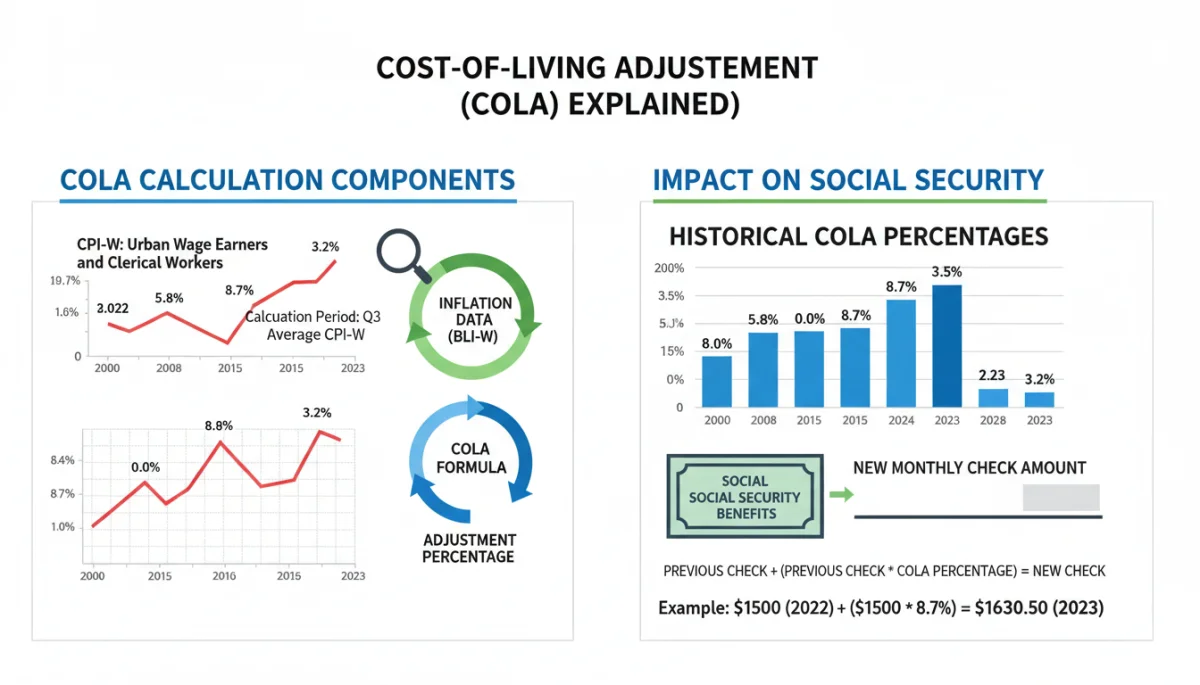
COLA calculations are not arbitrary; they are based on specific economic indicators. The primary measure used is the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). This index tracks the prices of goods and services commonly purchased by urban workers, providing a snapshot of inflation.
How COLA is Calculated
The calculation of COLA involves comparing the average CPI-W from the third quarter of the current year to the third quarter of the last year a COLA was enacted. If there’s an increase, that percentage difference becomes the COLA for the upcoming year. This methodology ensures that the adjustment reflects recent inflationary trends, providing a timely response to economic shifts.
- The CPI-W is the key inflation metric.
- Comparisons are made between third-quarter data.
- A positive increase in CPI-W triggers a COLA.
- The COLA percentage directly reflects the inflation rate observed.
Understanding this process is crucial for beneficiaries, as it demystifies how their annual benefit adjustments are determined. It underscores the government’s commitment to supporting the financial stability of those who rely on Social Security.
In essence, COLA acts as a financial buffer, preventing a static benefit amount from being devalued by rising costs. It’s a proactive measure that aims to keep Social Security benefits relevant and effective in a dynamic economic environment, directly impacting the daily lives of retirees.
The Projected 2.8% COLA for 2026: An Overview
The anticipation of a 2.8% Cost-of-Living Adjustment (COLA) for 2026 has significant implications for millions of Social Security beneficiaries. This projected increase, while not yet official, offers a glimpse into the financial adjustments that retirees and other recipients can expect. A 2.8% COLA represents a moderate increase, reflecting current economic forecasts and inflationary pressures.
This projected percentage is derived from economic models and preliminary CPI-W data, indicating a steady, albeit not dramatic, rise in the cost of living. For beneficiaries, this means a tangible boost to their monthly income, designed to offset some of the inflationary impacts experienced over the past year.
Historical COLA Trends and 2026 Projections
Looking at historical COLA figures provides valuable context. Over the past few decades, COLA percentages have varied widely, from years with no increase to periods of significant adjustments. The 2.8% projection for 2026 falls within a typical range, signaling a return to more moderate adjustments after some volatile years.
- COLA percentages fluctuate based on economic conditions.
- Recent years have seen both high and low adjustments.
- The 2.8% projection suggests a stable, moderate inflationary environment.
- Understanding past trends helps set expectations for future adjustments.
This projection allows beneficiaries and financial planners to begin strategizing for the upcoming year. While the final figure will be announced later, this early estimate provides a critical baseline for financial planning and budgeting. It’s a key piece of information for anyone relying on Social Security benefits.
The 2.8% COLA for 2026 is more than just a number; it’s a reflection of the economic climate and a direct influence on the financial stability of countless individuals. It highlights the continuous need for beneficiaries to stay informed and adapt their financial plans accordingly.
Direct Impact on Your Retirement Benefits
A 2.8% Cost-of-Living Adjustment (COLA) directly translates into a higher monthly Social Security payment for beneficiaries. This increase is applied to your current benefit amount, meaning that if you receive, for example, $1,500 per month, a 2.8% COLA would add $42 to your check, bringing it to $1,542. While seemingly modest, these adjustments accumulate over time and are crucial for maintaining financial equilibrium in retirement.
It’s important to remember that this increase is designed to help you keep up with rising expenses, not necessarily to provide a substantial boost in discretionary income. The goal of COLA is to preserve purchasing power, ensuring that your benefits can still cover the same basket of goods and services year after year.
Calculating Your New Benefit Amount
To calculate your estimated new benefit amount, simply multiply your current monthly benefit by 1.028 (1 + 0.028). This straightforward calculation allows you to quickly see the direct financial impact of the 2026 COLA. For those with higher current benefits, the dollar amount of the increase will naturally be larger, and vice versa.
- Current benefit amount x 1.028 = New estimated benefit.
- The increase is a direct percentage of your existing payment.
- This adjustment helps offset inflation, not increase wealth.
- Beneficiaries should factor this into their annual budget.
Beyond the direct increase, there are other considerations. For instance, some beneficiaries may find that a higher Social Security income could affect their eligibility for certain income-tested programs or the taxation of their Social Security benefits. These are important nuances to consider as part of your overall financial planning.
Ultimately, the 2.8% COLA for 2026 is a positive adjustment that reinforces the protective nature of Social Security. It provides a necessary financial boost, helping retirees to navigate the ongoing challenge of rising living costs with greater confidence.
Broader Economic Implications for Seniors
The 2.8% COLA for 2026 extends beyond individual benefit checks, carrying broader economic implications for the senior population. This adjustment influences spending patterns, impacts local economies, and plays a role in the overall financial health of a significant demographic. When seniors have more purchasing power, they are more likely to spend, which can stimulate local businesses and contribute to economic activity.
However, the effectiveness of COLA in truly maintaining purchasing power is a frequent subject of debate. While the CPI-W is a broad measure, some argue that it doesn’t fully capture the specific inflation rates experienced by seniors, particularly regarding healthcare costs and housing, which often rise faster than general inflation.
Inflationary Pressures and Senior Spending
Seniors often face unique inflationary pressures. Healthcare expenses, prescription drugs, and long-term care costs can consume a larger portion of their income compared to younger demographics. Therefore, a 2.8% COLA, while helpful, might not fully mitigate the impact of these specific, often higher, cost increases.
- COLA helps offset general inflation.
- Seniors face unique cost pressures, especially in healthcare.
- The effectiveness of COLA can vary based on individual spending habits.
- Increased benefits can stimulate local economies.
The cumulative effect of COLA adjustments over many years is what truly matters for long-term financial stability. Consistent, albeit modest, increases help prevent a drastic erosion of benefits. This continuous adjustment is a cornerstone of Social Security’s design, aiming to provide a reliable income stream throughout retirement.
Therefore, while the 2.8% COLA is a positive development, seniors must continue to be vigilant about their budgeting and financial planning, especially considering the specific costs they face. It’s a piece of the larger economic puzzle that impacts their overall well-being.
Financial Planning Strategies for the 2026 COLA
With the projected 2.8% COLA for 2026, it’s an opportune moment for retirees and those nearing retirement to reassess their financial planning strategies. This adjustment, though moderate, can be integrated into a comprehensive financial outlook to optimize your retirement income and expenses. Proactive planning ensures that you maximize the benefit of this increase and address any potential financial shifts.
One key strategy is to update your annual budget to reflect the new Social Security income. Understanding exactly how much more you will receive allows for more precise allocation of funds, whether for essential expenses, discretionary spending, or savings. This also helps in identifying any areas where adjustments might be needed due to other rising costs.
Adjusting Your Retirement Budget
Integrating the COLA into your budget involves more than just adding the extra funds. It means looking at your overall financial picture. Consider how this increase might affect your tax liability, especially if it pushes you into a higher income bracket or impacts the taxation of your Social Security benefits. Consulting a financial advisor can provide clarity on these complex interactions.
- Update your budget with the new COLA amount.
- Assess potential tax implications of increased income.
- Review healthcare costs, which often outpace general inflation.
- Consider how additional funds could be saved or invested.
Another important aspect is to review your healthcare costs. While Social Security benefits increase, Medicare premiums, particularly Part B, often rise as well. These increases can sometimes offset a portion of the COLA, making it crucial to factor them into your financial calculations. Being aware of these potential offsets allows for more realistic budgeting.
Ultimately, the 2026 COLA provides a valuable opportunity to fine-tune your retirement plan. By meticulously adjusting your budget, understanding tax implications, and consulting with financial professionals, you can ensure that this benefit increase effectively supports your long-term financial security.
Potential Challenges and Future Outlook
While the 2.8% COLA for 2026 offers a welcome boost to Social Security beneficiaries, it’s important to acknowledge potential challenges and consider the future outlook of the program. The long-term solvency of Social Security is a recurring concern, influenced by demographic shifts, economic growth, and legislative decisions. Understanding these broader dynamics helps beneficiaries contextualize annual COLA adjustments.
One significant challenge is the ongoing debate about the adequacy of COLA calculations. Critics argue that the CPI-W, while broadly representative, may not accurately reflect the specific inflation experienced by seniors, particularly concerning healthcare and housing costs. This discrepancy can lead to a gradual erosion of purchasing power over many years, despite annual adjustments.
Long-Term Solvency and Policy Debates
The financial health of the Social Security trust funds is continuously monitored, with projections often indicating future shortfalls if no legislative action is taken. These discussions often revolve around potential solutions such as adjusting the full retirement age, modifying the COLA calculation method, or increasing payroll taxes. Such policy debates can create uncertainty for future beneficiaries.
- Debate exists over the accuracy of CPI-W for seniors.
- Long-term solvency of Social Security remains a concern.
- Potential policy changes could impact future benefits.
- Beneficiaries should stay informed on legislative developments.
Furthermore, the economic environment itself presents challenges. Unforeseen inflation spikes or prolonged periods of low economic growth could impact future COLA percentages, making long-term financial planning more complex. Beneficiaries must remain adaptable and consider diversified income streams beyond Social Security.
Despite these challenges, Social Security remains a cornerstone of retirement security for millions. The 2.8% COLA for 2026 is a testament to its adaptive nature, but it also serves as a reminder to engage with the broader financial and policy discussions that will shape its future.
Maximizing Your Benefits Beyond COLA
While the annual Cost-of-Living Adjustment (COLA) is crucial for maintaining the purchasing power of your Social Security benefits, maximizing your overall retirement income involves more than just COLA. Strategic planning and informed decisions can significantly enhance your financial well-being in retirement, complementing the increases provided by the 2.8% COLA for 2026.
One primary strategy is to consider your claiming age. Delaying Social Security benefits beyond your full retirement age, up to age 70, can result in significantly higher monthly payments due to delayed retirement credits. This increase is permanent and can provide a more substantial boost to your income than annual COLA adjustments alone.
Exploring Additional Income Streams
Diversifying your income sources is another powerful way to maximize your benefits. Relying solely on Social Security can be risky, especially given potential future adjustments or economic volatility. Exploring options such as part-time work, investments, pensions, or annuities can create a more robust financial safety net.
- Consider delaying Social Security claims for higher benefits.
- Diversify income streams beyond Social Security.
- Consult financial advisors for personalized strategies.
- Understand how taxes impact your overall retirement income.
Moreover, understanding the taxation of Social Security benefits is vital. A portion of your benefits may be taxable depending on your combined income. Strategic tax planning, such as utilizing tax-advantaged retirement accounts, can help minimize your tax burden and effectively increase your net income.
Engaging with a qualified financial advisor can provide personalized guidance tailored to your specific situation. They can help you navigate complex financial decisions, optimize your claiming strategy, and develop a comprehensive plan that integrates your Social Security benefits with other assets to achieve your retirement goals.
By taking a holistic approach to your retirement finances, you can ensure that the 2.8% COLA for 2026 is just one component of a larger, well-structured plan designed to maximize your financial security and quality of life in your golden years.
| Key Aspect | Description |
|---|---|
| 2026 COLA Projection | A projected 2.8% Cost-of-Living Adjustment for Social Security benefits. |
| Impact on Benefits | Directly increases monthly Social Security payments to offset inflation. |
| Financial Planning | Requires budget adjustments and consideration of tax implications for retirees. |
Frequently Asked Questions About the 2026 Social Security COLA
The primary purpose of the Social Security Cost-of-Living Adjustment (COLA) is to protect the purchasing power of beneficiaries’ benefits from inflation. It ensures that the value of their payments does not diminish over time due to rising costs of goods and services, helping them maintain their standard of living.
The 2026 COLA, like previous adjustments, is determined by comparing the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) from the third quarter of 2025 to the third quarter of 2024. The percentage increase in CPI-W directly translates to the COLA percentage.
Yes, an increase in your Social Security benefits due to COLA can sometimes be offset by rising Medicare Part B premiums. While the COLA increases your gross benefit, the net increase might be smaller if Medicare premiums also increase, as they are often deducted directly from Social Security checks.
No, the 2.8% COLA for 2026 is currently a projection based on economic forecasts and preliminary data. The official COLA announcement is typically made in October of the preceding year (e.g., October 2025 for the 2026 COLA), after all necessary inflation data has been collected and analyzed by the SSA.
To prepare for the 2026 Social Security Update, beneficiaries should review their current budget, factor in the projected 2.8% COLA increase, and consider any potential impacts on taxes or eligibility for other programs. Consulting a financial advisor for personalized guidance is also highly recommended for comprehensive planning.
Conclusion
The projected 2.8% Cost-of-Living Adjustment for 2026 represents a crucial adjustment for Social Security beneficiaries, aiming to preserve their purchasing power in an evolving economic landscape. Understanding how COLA is calculated, its direct impact on benefits, and its broader economic implications is essential for effective retirement planning. While this increase offers a necessary financial boost, it also underscores the importance of proactive financial management, including budgeting, tax considerations, and exploring diversified income streams. As we move towards 2026, staying informed about these updates and adapting personal financial strategies will be key to ensuring long-term financial security and well-being in retirement.
